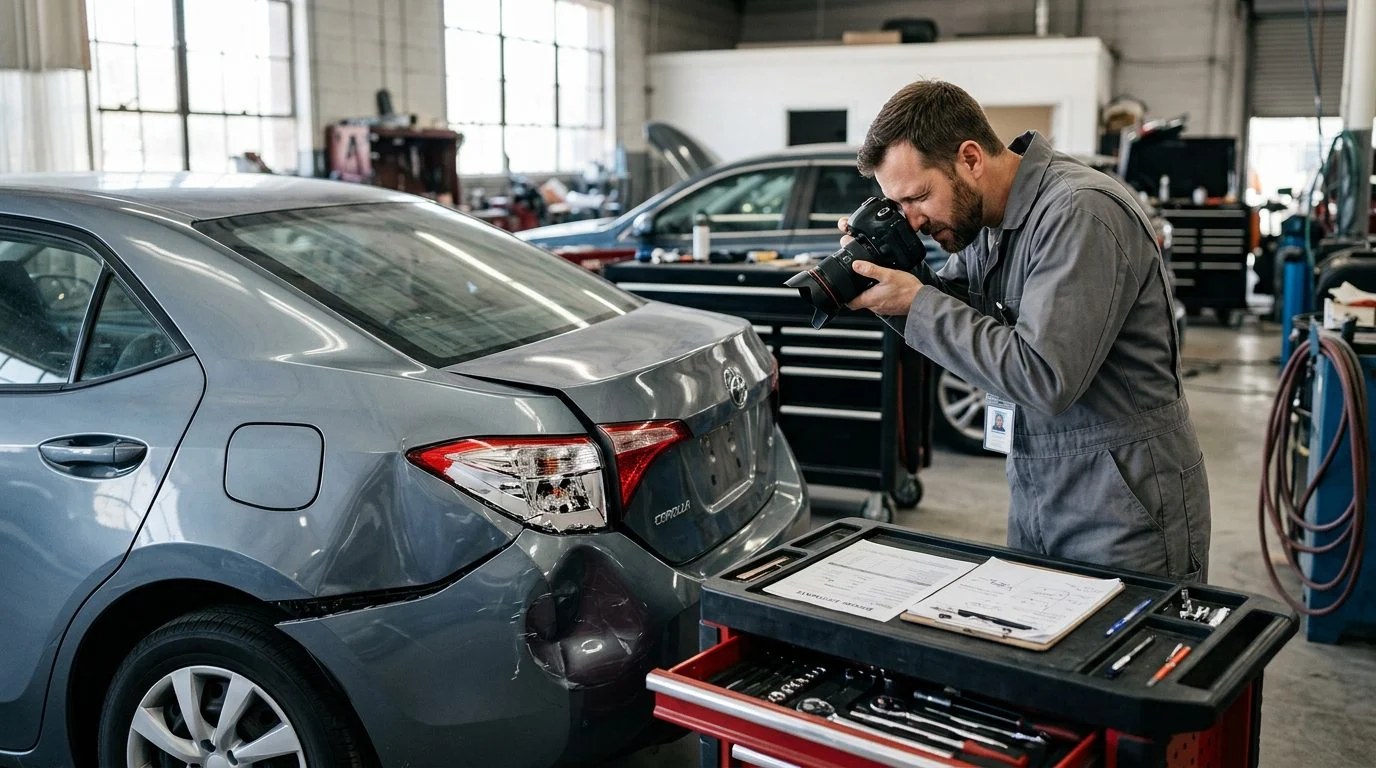
Wrongful Death & Car Accidents | New Mexico
Adjuster Calling After a Fatal Car Accident? Talk to Our Team First
The insurance adjuster works for the insurance company, not for your family. El Gringo Law represents families in wrongful death car accident matters across New Mexico. Your first consultation is free, confidential, and comes with no obligation to continue.
By Josh Wood · Published November 7, 2026
If an insurance adjuster is calling after a death in a car accident in New Mexico, you don’t have to answer every question on the first call. Stay calm, share basic facts, ask for the adjuster’s details in writing, and say you need time. This guide covers what to say, what to avoid, and what to keep while the claim is open.
Why the Insurance Adjuster Is Calling So Soon
An insurance adjuster works for an insurance company and evaluates claims on that company’s behalf. The call may come while your family is still in shock. You don’t have to be ready to talk.
Calls can start quickly after a crash. Sometimes they arrive before the family has had time to sit down together. The adjuster looks at fault, reviews reports, and estimates what the company may pay. Your answers become part of the company’s file.
Expect two kinds of calls. The other driver’s insurer may contact you to look into that driver’s role in the crash. Your own insurer may call about coverage under your policy. The purposes differ, so handle both with the same care.
Coverage matters too. Collision coverage, property-damage liability coverage, and injury coverage address different kinds of losses in auto crashes. Ask which coverage each call is about.
If insurance calls are piling up while you grieve, you don't have to sort them out alone, and we're glad to talk through your family's situation. Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Who Has the Claim After a Death in a New Mexico Crash
In New Mexico, the personal representative of the deceased person brings the wrongful death action. Family members don’t each file on their own. Under NMSA 1978, § 41-2-3, every such action is brought by and in the name of the personal representative.
The underlying right comes from § 41-2-1. A person whose wrongful act or neglect causes a death can be liable in damages. That is true when the same act would have let the injured person recover had death not occurred.
Under NMSA § 41-2-3, the jury in every such action may give such damages, compensatory and exemplary, as they deem fair and just. Under NMSA § 41-2-3, the jury, taking into consideration the pecuniary injury resulting from the death to the surviving party entitled to the judgment, or any interest in the judgment, recovered in such action, also has regard to the mitigating or aggravating circumstances attending the wrongful act, neglect or default. How any amount is set depends on the facts.
New Mexico also uses fault-based rules. The question of who caused the crash shapes what the insurer will discuss. Because the personal representative files the action, family members should talk with each other before taking a position with the insurer.
What to Say on the First Call
On the first call, share only basic facts and ask for the adjuster’s details in writing. Keep the rest for later, when you have time to review the situation.
- Give your name and your relationship to the person who died.
- Give the date and location of the crash.
- Say, “I’m still gathering information, and I need time before I discuss details.”
- Ask for the adjuster’s name, company, claim number, and direct phone number, in writing.
- If you have a lawyer, give that lawyer’s name. Ask that future contact go through them.
You can end the call and call back later. Write down the time, the adjuster’s name, and what was said while it’s fresh.
What Not to Say to the Adjuster
Don’t admit fault, guess about the crash, or agree to a dollar amount on the phone. Each of these can change how the claim is handled.
Don’t apologize for the crash or admit fault. A sentence that sounds like an admission can be quoted back in the claim file.
Don’t guess about speed, distance, or what the other driver could have seen. New Mexico adopted comparative negligence, as stated in the committee commentary to UJI 13-2218 NMRA. Under UJI 13-2218, when comparative negligence is an issue in the lawsuit and there is no apportionment of negligence among defendants or non-parties, a percentage of fault assigned to the injured person reduces the total damages. A small guess can still affect the numbers.
Don’t describe the final moments, the injuries, or the medical care beyond what identifies the claim. Don’t estimate the value of the loss before you understand the full picture.
Don’t comment on the person’s habits, job, or past health. Those comments can be quoted back and used to question the claim.
Recorded Statements, Early Offers, and Releases
Before you give a recorded statement or answer an early offer, ask for time and read the terms. These steps protect your options while you learn the full picture.
You can ask for questions in writing first. You can also ask to speak after you’ve talked with a lawyer.
An early offer can arrive before anyone knows the full losses. Don’t respond on the spot. New Mexico’s Rule 11-408 NMRA generally keeps offers and compromise talks out of evidence used to prove or disprove a claim’s validity or amount. That rule has listed exceptions, and it governs evidence in court. It does not tell you whether an offer is fair.
A release needs careful reading. Under § 41-3-4, a release by an injured person of one joint tortfeasor, meaning a person who shares legal responsibility for the same injury, does not discharge the others unless the release says so. It also reduces the claim against the others by the amount paid, or by a greater amount if the release provides that the total claim shall be reduced by more. Check which parties a release names and what it says about everyone else.
Keep a written log of every call and letter. Include dates, names, and what was said or offered.
Evidence to Protect While the Claim Is Open
Keep the crash report, photos, witness names, insurance letters, and any pay records. Ask before any vehicle is repaired, sold, or scrapped.
New Mexico’s accident-report statute, Section 66-7-213, provides that, except where that section itself allows it, an accident report may not be used as evidence in a civil or criminal trial that arises out of the accident. The statute lists exceptions. Still, keep a copy of any report you file or receive.
Vehicle information can matter in a fatal crash. Ask the insurer and any tow or repair yard to hold the vehicle until the claim is reviewed.
If the person who died earned income, pay records and tax forms help show the financial loss. The wrongful death statute refers to the pecuniary injury that results from the death. Keep these records together in one folder.
Photos of the scene, the vehicles, and any visible injuries should be saved in original form. Save the names and contact details of anyone who saw the crash.
Not sure what your next step is?
Talk it through with our team — the first consultation is free, confidential, and carries no obligation.
Frequently Asked Questions
How long do I have to file a wrongful death claim in New Mexico?
Under NMSA 1978, § 41-2-2, every action instituted by virtue of this section and the preceding section (41-2-1 NMSA 1978) must be brought within three years after the cause of action accrues. Under § 41-2-2, it accrues on the date of death. Don’t wait for insurance talks to finish before you check this deadline.
Do I have to talk to the adjuster at all?
You choose what you discuss, when, and in what form. You can ask a lawyer to handle contact with the insurer.
Can an early offer be changed later?
The release’s terms decide what it does to other claims. Under § 41-3-4, a release can reduce or leave other claims in place, depending on its wording. Review every term before you respond.
Does the insurer’s number decide what the claim is worth?
No. The insurer’s evaluation is its own view. The value of a wrongful death claim depends on the facts of the case.
If You Are Handling This Claim for Your Family
If you are fielding insurance calls for a family member who died, you don’t have to work through the claim alone. You may be grieving while handling paperwork and phone calls. Each decision can feel heavy.
Our team is ready to talk through your family’s facts. The first consultation is free, confidential, and comes with no obligation to continue.
Josh Wood is the lawyer responsible for this page. He is licensed in New Mexico and Arizona. You can reach our team through the contact form on our website when you’re ready.
How We Can Help Your Family
Protecting Your Claim
Insurance adjusters are trained to gather information for their company. We help you understand what to say and what to hold back while you grieve.
Answers Before You Sign
Before you sign a release or agree to a recorded statement, consider reviewing it with a lawyer. We explain what each document asks of you.
Compassionate Listening
Losing someone in a car accident is painful. Our team listens first and takes the time to understand your family's situation.
Support Staff Who Keep Things Moving
Our assistants and office staff help coordinate calls, records, and paperwork so you have fewer details to track during a hard time.
Before You Respond to the Adjuster
Adjusters may ask for a recorded statement, medical records, or a quick settlement decision. Take a breath, write down who called and what they asked, and consider speaking with a lawyer before agreeing to anything.
Common Requests From Insurance Adjusters
Recorded Statements
Adjusters often ask to record a conversation about the crash. Ask for a lawyer's guidance before you give one.
Medical and Records Authorizations
Forms that let the insurer obtain medical or employment records can reach far beyond the accident. Review them before you sign.
Early Settlement Offers
A quick offer may not reflect the full impact of your loss. Ask a lawyer to review any offer before you respond.
Releases
A release can end your ability to pursue more compensation later. Understand what you are signing before you return it.